Beyond Samsung and SK Hynix: What October 29–30 DART Filings Reveal About Korea's Second-Wave AI Bottlenecks Across KOSPI and KOSDAQ
While foreign institutional flows in Korea crowd into the two HBM mega-caps, October 29–30 DART filings show operating profit surging +259.4% YoY at KOSPI substrate maker Daeduck Electronics and +596.1% QoQ at KOSDAQ wafer-transfer robot specialist Raon Robotics.
As of 2026.10.31 (Source: Korean FSS DART K-IFRS Preliminary 3Q26 Earnings & Single-Sales Contract Filings filed 2026.10.29–2026.10.30) · Growth rates, ratios, and baselines not printed directly in the primary releases were calculated by me from the disclosed financial statements and are marked (Calc.) in the tables.
When global investors look at the Korea Exchange (KRX), they frequently treat KOSPI as a two-stock memory proxy (Samsung Electronics 005930.KS and SK Hynix 000660.KS) and dismiss KOSDAQ as a retail-driven biotech and small-cap index. That framing misses how South Korea's industrial and semiconductor ecosystem is actually structured: KOSPI houses the heavy electrical grid transformers, multilayer ceramic capacitors (MLCCs), and flip-chip ball grid array (FC-BGA) substrates required to power AI clusters, while KOSDAQ houses the specialized cleanroom equipment, silicon carbide (SiC) etch consumables, and vacuum wafer-transfer robotics that go inside Samsung's and SK Hynix's fabs.
To test whether upstream memory CapEx and global data-center buildouts are flowing down into the broader Korean market, I audited seven primary K-IFRS preliminary earnings releases (영업(잠정)실적 공정공시) and mandatory single-sales supply contracts (단일판매ㆍ공급계약체결) filed on DART between October 29 and October 30, 2026 across three KOSPI issuers and four KOSDAQ issuers [1][2][3][4][5][6][7].
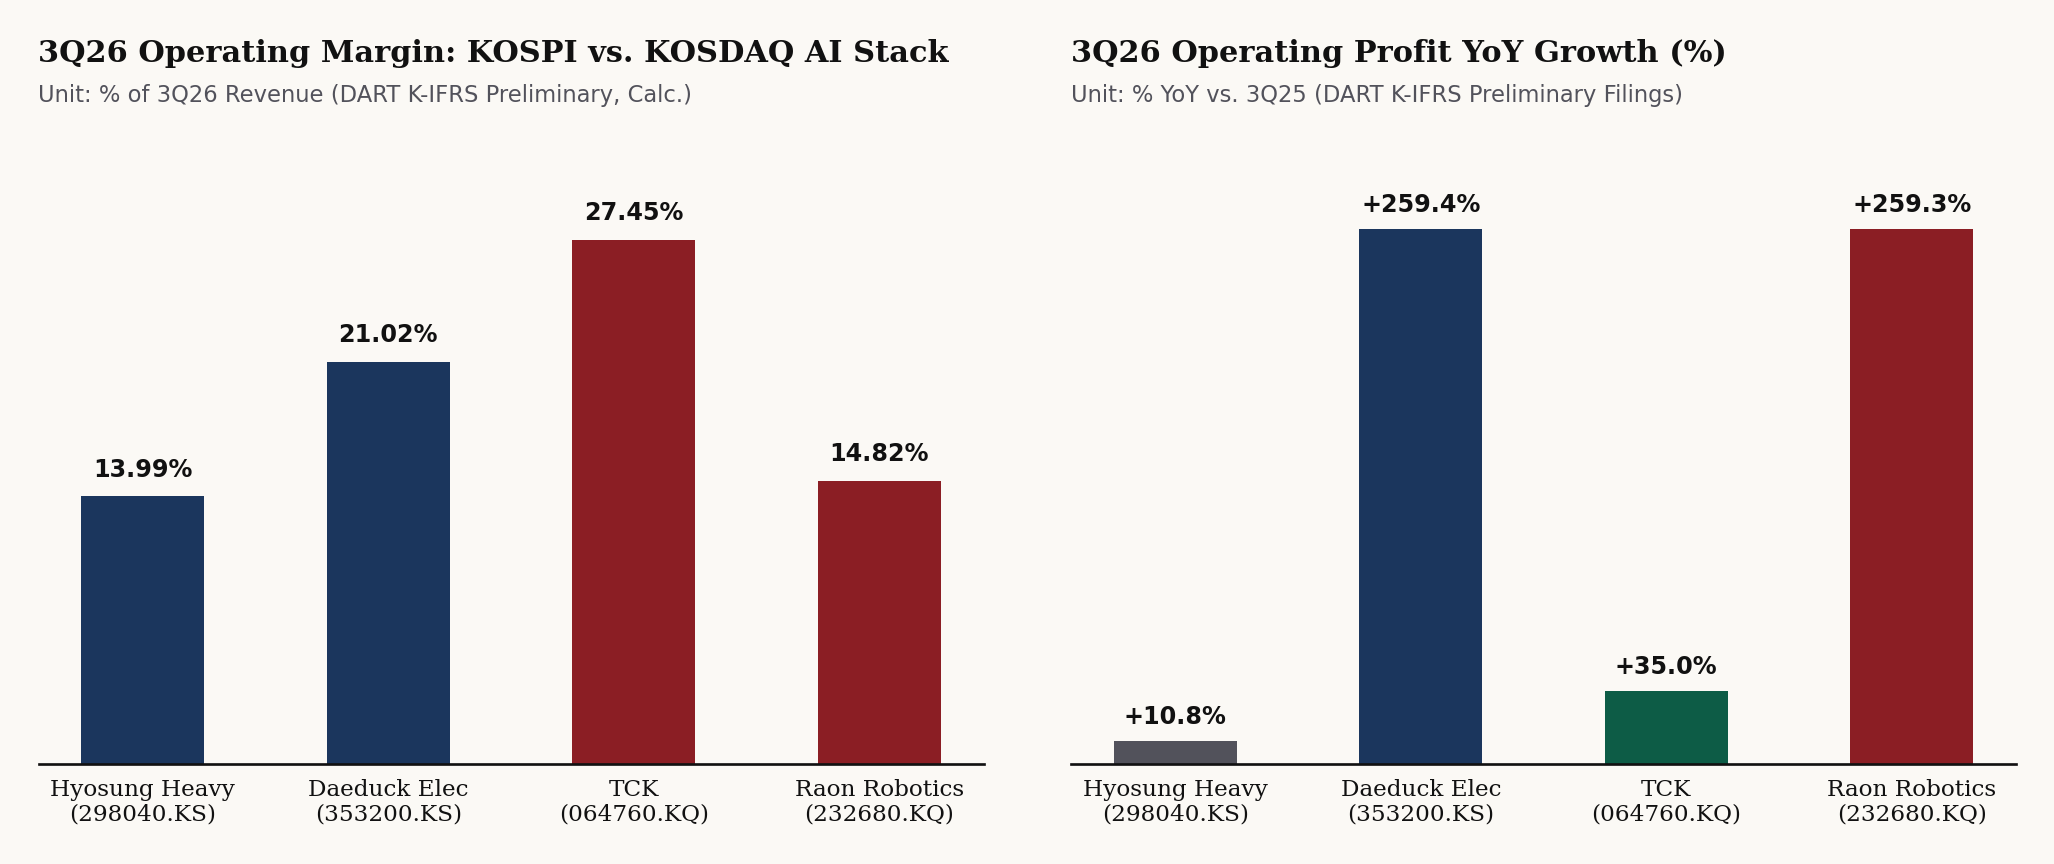
Left: 3Q26 operating margin comparison across KOSPI (Hyosung Heavy 298040.KS, Daeduck Electronics 353200.KS) and KOSDAQ (TCK 064760.KQ, Raon Robotics 232680.KQ). Right: 3Q26 YoY operating profit growth from official DART preliminary filings [1][2][4][5].
| Issuer (Market & Ticker) | Verified Oct 29–30 DART Filing Figures (3Q26 / Contract) |
|---|---|
| Hyosung Heavy Industries (KOSPI: 298040.KS) |
3Q26 Rev 1,740,635M KRW (+3.18% QoQ, +7.17% YoY; 9M26 4,785,822M KRW, +13.26% YoY); OP 243,455M KRW (-7.88% QoQ, +10.76% YoY; 9M26 660,064M KRW, +35.69% YoY) → 13.99% 3Q26 OPM (Calc.); Pre-tax income 280,237M KRW (+18.31% QoQ, +43.25% YoY); Net profit 226,303M KRW (+31.77% QoQ, +49.11% YoY) [1] |
| Daeduck Electronics (KOSPI: 353200.KS) |
3Q26 Rev 418,115M KRW (+4.3% QoQ, +46.1% YoY; 9M26 1,165,404M KRW, +55.9% YoY); OP 87,871M KRW (+25.0% QoQ, +259.4% YoY; 9M26 209,446M KRW, +941.4% YoY) → 21.02% 3Q26 OPM (Calc. vs. 8.54% in 3Q25); Net profit 54,376M KRW (+133.6% YoY) [2] |
| Samsung Electro-Mechanics (KOSPI: 009150.KS) |
MLCC supply contract for 879,285.4M KRW (US$658.0M at 1,336.30 KRW/USD) = 7.8% of FY25 consolidated revenue (11,314,459.2M KRW); period 2026.12.21–2027.12.21; zero advance payment; counterparty withheld until 2027.12.21 [3] |
| TCK (Tokai Carbon Korea) (KOSDAQ: 064760.KQ) |
3Q26 standalone Rev 110,102M KRW (+16.05% QoQ, +38.95% YoY; 9M26 300,366M KRW, +30.44% YoY); OP 30,219M KRW (+12.55% QoQ, +35.04% YoY; 9M26 85,622M KRW, +31.02% YoY) → 27.45% 3Q26 OPM (Calc.; 9M26 OPM 28.51% Calc.) [4] |
| Raon Robotics (KOSDAQ: 232680.KQ) |
3Q26 standalone Rev 26,535M KRW (+45.9% QoQ, +104.7% YoY; 9M26 58,863M KRW, +51.3% YoY); OP 3,933M KRW (+596.1% QoQ vs. 565M KRW, +259.3% YoY vs. 1,095M KRW) → 14.82% 3Q26 OPM (Calc. vs. 3.11% in 2Q26) [5] |
| Wort & Withtech (KOSDAQ: 396470.KQ / 348350.KQ) |
Wort: 1,638.0M KRW THC contract with Samsung Electronics (10.76% of FY25 rev 15,220.9M KRW; Hwaseong/Pyeongtaek fabs through 2027.05.31) [6]. Withtech: 13,044.0M KRW TMS O&M contract with Samsung Electronics (22.56% of FY25 rev 57,807.0M KRW; 2026.11.01–2027.12.31) [7] |
1. KOSPI's Second Wave: High-Voltage Transformers, Package Substrates & High-Cap MLCCs
On the KOSPI board, three October 30 filings show how AI infrastructure spending extends beyond memory wafers into power delivery and board-level interconnects:
- Hyosung Heavy Industries (
298040.KS) — Sustained Double-Digit Grid Margins: Hyosung Heavy is one of Korea's premier ultra-high-voltage transformer and switchgear exporters serving U.S. and global grid upgrades. In 3Q26, consolidated revenue rose 7.17% YoY (3.18% QoQ) to 1,740,635 million KRW, while 9-month cumulative operating profit rose 35.69% YoY to 660,064 million KRW [1]. Even with a slight sequential dip in operating profit (-7.88% QoQ to 243,455 million KRW, or 13.99% OPM Calc. vs. 15.67% in 2Q26), pre-tax continuing income jumped 18.31% QoQ (+43.25% YoY) to 280,237 million KRW and net profit climbed 31.77% QoQ (+49.11% YoY) to 226,303 million KRW [1]. - Daeduck Electronics (
353200.KS) — Operating Leverage in Semiconductor Substrates: Semiconductor package substrate makers suffered a multi-year utilization trough in 2024–2025, which makes their operating leverage during a recovery extreme. Daeduck's 3Q26 revenue expanded 46.1% YoY (+4.3% QoQ) to 418,115 million KRW, but operating profit surged 259.4% YoY (+25.0% QoQ) from 24,448 million KRW to 87,871 million KRW—lifting its operating margin by +12.48 percentage points YoY from 8.54% to 21.02% (Calc.) [2]. Across the first nine months of 2026, operating profit is up 941.4% YoY (209,446 million KRW vs. 20,112 million KRW in 9M25) [2]. - Samsung Electro-Mechanics (
009150.KS) — A $658M One-Year MLCC Supply Commitment: On October 30, Samsung Electro-Mechanics disclosed a single one-year MLCC supply contract valued at 879,285.4 million KRW (US$658.0 million converted at the October 29 base rate of 1,336.30 KRW/USD), equivalent to 7.8% of its entire FY25 consolidated revenue (11,314,459.2 million KRW) [3]. For foreign investors reading Korean contract disclosures, note two standard KRX mechanics in Section 6 and Section 8 of the filing: there is no upfront deposit (계약금ㆍ선급금 유무: 무), and the global counterparty's name is legally withheld under trade-secret protection until December 21, 2027 [3].
2. KOSDAQ's Fab-Floor Specialists: Etch Consumables, Vacuum Robotics & Pyeongtaek Orders
Whereas KOSPI's hardware suppliers sell into global data centers and board assemblers, KOSDAQ's semiconductor tier captures the physical utilization and cleanroom expansion of Korean memory fabs:
- TCK (
064760.KQ) — 27.45% Operating Margin on Etch-Chamber Consumables: TCK manufactures solid silicon carbide (SiC) focus rings used inside plasma etch chambers for 3D NAND and DRAM. Because SiC rings erode during plasma etching, TCK's revenue tracks actual fab wafer runs rather than greenfield announcements. In its October 29 DART filing, 3Q26 revenue rose 16.05% QoQ (+38.95% YoY) to 110,102 million KRW and operating profit reached 30,219 million KRW (+12.55% QoQ, +35.04% YoY)—a 27.45% operating margin (Calc.), with 9M26 operating margin at 28.51% (Calc.) on 300,366 million KRW of revenue [4]. - Raon Robotics (
232680.KQ) — 6x Sequential Operating Profit Inflection: Raon Robotics builds vacuum wafer-transfer robots and automation modules for semiconductor manufacturing equipment. On October 30, it reported 3Q26 standalone revenue of 26,535 million KRW (+45.9% QoQ, +104.7% YoY) and operating profit of 3,933 million KRW (+596.1% QoQ from 565M KRW in 2Q26, and +259.3% YoY), driving standalone OPM from 3.11% in 2Q26 to 14.82% in 3Q26 (Calc.) [5]. - Wort (
396470.KQ) & Withtech (348350.KQ) — Direct Contract Visibility Into Samsung's Fabs: Earlier, in our Samsung Electronics 3Q26 note, we observed that Samsung's 9M26 cash PP&E CapEx stood at 56.9T KRW against an 84.4T KRW annual plan (leaving ~27.5T KRW for 4Q26). On October 30, two KOSDAQ fab-equipment specialists disclosed direct contracts with Samsung Electronics: Wort signed a 1,638.0 million KRW contract (10.76% of its FY25 revenue of 15,220.9M KRW) to supply ultra-precision temperature and humidity control (THC) units to Samsung's Hwaseong and Pyeongtaek campuses through May 31, 2027 (settled 100% in cash within 30 days of delivery) [6], while Withtech signed a 13,044.0 million KRW contract (22.56% of its FY25 revenue of 57,807.0M KRW) for industrial emission monitoring (TMS) maintenance at Samsung Electronics from November 1, 2026 through December 31, 2027 [7].
3. Falsifiable Hypothesis for 4Q26 KRX Filings
My working hypothesis for foreign investors positioning across KRX is that 4Q26 backend fab-equipment and consumable revenue on KOSDAQ (TCK, Raon Robotics, Wort) will accelerate sequentially as Samsung Electronics executes its implied ~27.5T KRW 4Q26 facility investment balance and SK Hynix ramps M15X. This hypothesis will be falsified if TCK's and Raon Robotics' 4Q26 revenue growth turns negative QoQ or if Wort's Hwaseong/Pyeongtaek delivery schedule (currently May 31, 2027) is pushed back via a DART contract amendment (기재정정) [4][5][6].
Sources
- DART Hyosung Heavy Industries (298040.KS) Preliminary Consolidated 3Q26 Earnings Fair Disclosure, 2026.10.30.
- DART Daeduck Electronics (353200.KS) Preliminary Consolidated 3Q26 Earnings Fair Disclosure, 2026.10.30.
- DART Samsung Electro-Mechanics (009150.KS) Single-Sales & Supply Contract Disclosure (MLCC), 2026.10.30.
- DART TCK (064760.KQ) Preliminary 3Q26 Earnings Fair Disclosure, 2026.10.29.
- DART Raon Robotics (232680.KQ) Preliminary 3Q26 Earnings Fair Disclosure, 2026.10.30.
- DART Wort (396470.KQ) Single-Sales & Supply Contract Disclosure (Samsung Electronics THC), 2026.10.30.
- DART Withtech (348350.KQ) Single-Sales & Supply Contract Disclosure (Samsung Electronics TMS), 2026.10.30.