October 2026 FOMC Statement & SEP Comparison: 3.75%-4.00% Hold, 10-2 Vote Split & Two 25bp Hike Dissents
Macro & FedFOMCInterest RatesSEP Dot Plot
As of 2026.10.30 | Research & Disclosure Note: This article is a personal research memo written by the author of Deep Growth Investing based on the official earnings releases and regulatory filings cited inline (figures calculated by the author from primary tables are labeled Author calculation). As of the writing date, I do not hold shares or positions in any of the companies discussed. This post is for informational and personal record-keeping purposes only and does not constitute investment advice or a solicitation to buy or sell any security.
On October 28, 2026, the Federal Open Market Committee (FOMC) released its policy statement and implementation note, maintaining the federal funds target range at 3-3/4 to 4 percent (3.75%–4.00%, midpoint 3.875%) [1][2]. When I compare the October 28 text sentence by sentence against the September 16, 2026 statement (where the FOMC raised the target range by 1/4 percentage point on a 12–0 vote) and the September Summary of Economic Projections (SEP) [3][4], the central takeaway is the 10–2 vote split in which both dissents favored another 25bp hike.
3-Line Summary (As of 2026.10.30):
- Policy Rate Held at 3-3/4 to 4% (Midpoint 3.875%), Vote Shifts from 12–0 to 10–2: While the FOMC maintained the target range at 3.75%–4.00% (IORB 3.90%, ON RRP 3.75% with $160B per-counterparty daily limit, Standing Repo & Primary Credit 4.0%), Lisa D. Cook and Beth M. Hammack both dissented in favor of raising the target range by 1/4 percentage point.
- Statement Wording Upgrade ('Solid' → 'Strong' Pace) & Q3 GDP 3.4%: Paragraph 1 upgraded economic activity from expanding at a "solid pace" (September) to a "strong pace" (October)—consistent with the Q3 2026 advance real GDP estimate of 3.4% (vs. 2.2% in Q2 2026)—while repeating verbatim that "Productivity growth is strong, and capital investment is robust."
- SEP Dot Plot Medians (4.1% End-2026) & U.S. Treasury Par Yields: In the September 2026 SEP (vs. June 2026), the median federal funds projection rose from 3.8% to 4.1% for end-2026 (with the 9th and 10th dots at 4.125%, +0.25%p above the current 3.875% midpoint) and from 3.6% to 4.1% for end-2027 (2028: 3.9% vs. 3.4% in June; 2029: 3.6%; longer-run: 3.2% vs. 3.1%). On October 28, U.S. Treasury par yields stood at 2Y 4.67% (-0.03%p), 10Y 5.05% (+0.06%p), and 30Y 5.37% (+0.07%p).
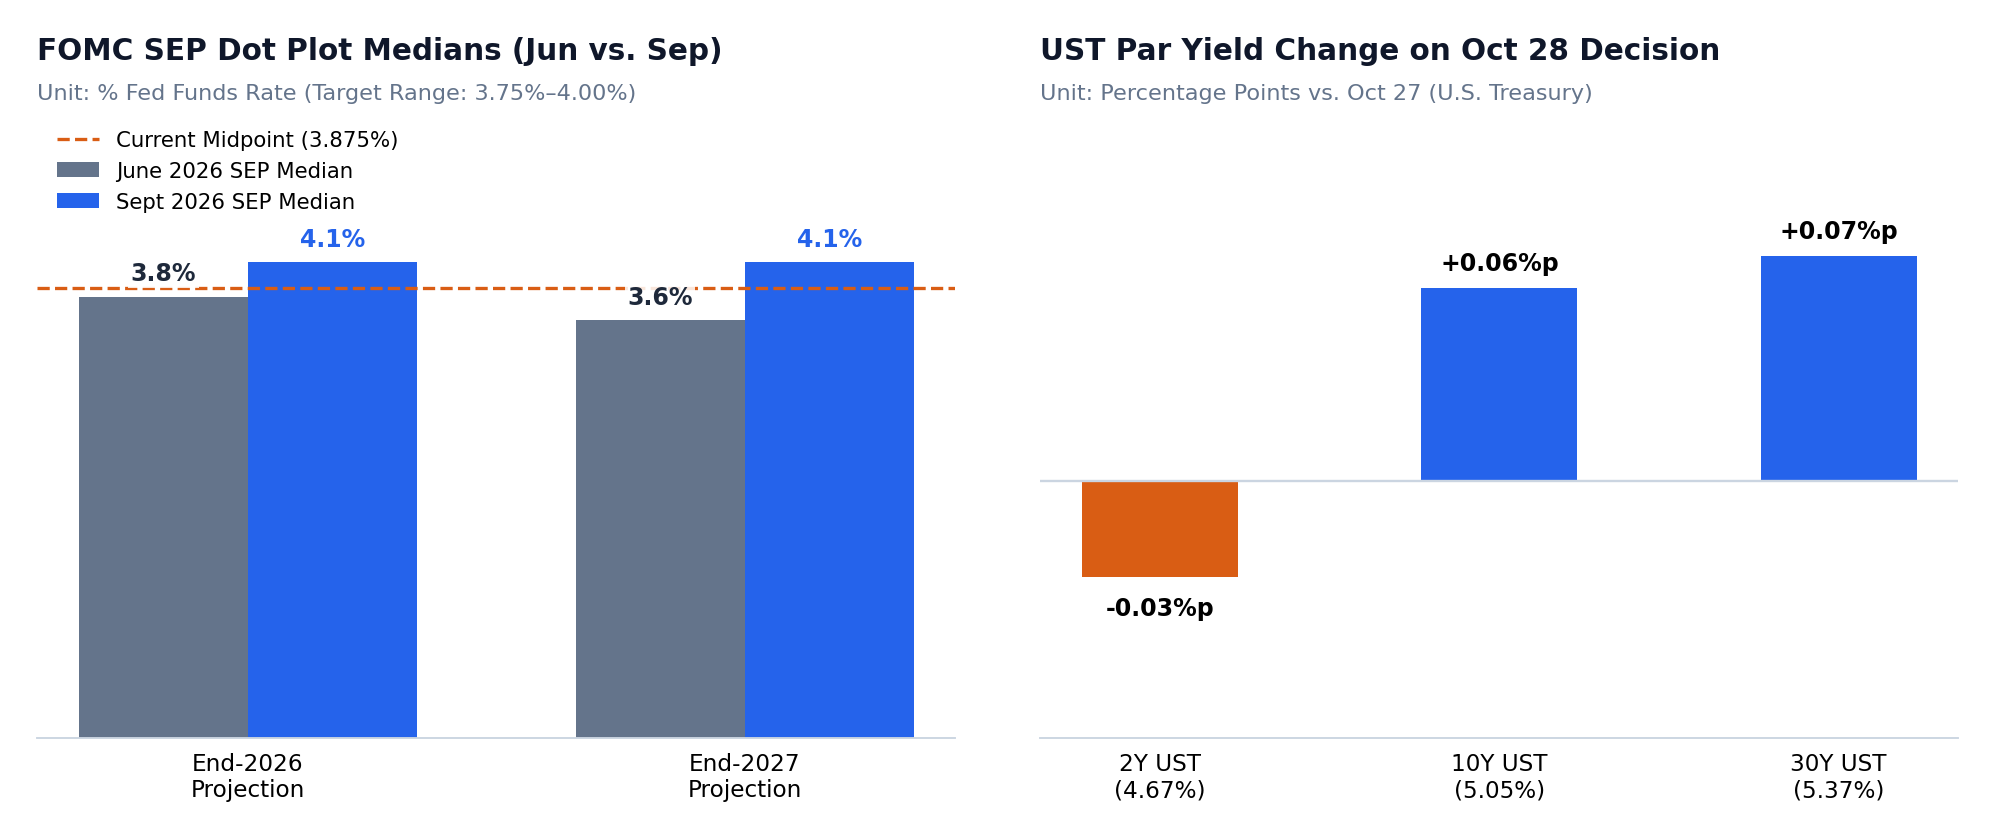
1. September vs. October 2026 FOMC Statement & SEP Comparison
| Item | September 16, 2026 FOMC / SEP | October 28, 2026 FOMC Statement |
|---|---|---|
| Federal Funds Target Range | Raised +0.25%p to 3.75% – 4.00% (midpoint 3.875%) | Maintained at 3.75% – 4.00% (IORB 3.90%, ON RRP 3.75%, Primary Credit 4.0%) |
| Vote Split & Dissents | 12 for, 0 against | 10 for, 2 against (Lisa D. Cook & Beth M. Hammack preferred +0.25%p hike) |
| Economic Activity & Investment Wording | Expanding at a "solid pace"; productivity strong, capital investment robust | Upgraded to "strong pace" (Q3 advance GDP 3.4% vs. Q2 2.2%; H1 revised 1.8% → 2.4%) |
| SEP Medians (Sept vs. June 2026) [4] | End-2026 Fed Funds: 4.1% (June 3.8%); End-2027: 4.1% (June 3.6%); 2026 GDP 2.3%, Unemployment 4.1%, PCE 3.7%, Core PCE 3.4% | Next SEP will be released at the December 8–9, 2026 FOMC meeting [5] |
| Treasury Par Yields (Oct 27 → Oct 28 → Oct 29) [6] | Oct 27: 2Y 4.70% / 10Y 4.99% / 30Y 5.30% | Oct 28: 2Y 4.67% (-0.03%p) / 10Y 5.05% (+0.06%p) / 30Y 5.37% (+0.07%p) (Oct 29: 4.61% / 4.98% / 5.32%) |
Primary Sources (Federal Reserve Board & U.S. Treasury)
- Federal Reserve FOMC Statement (October 28, 2026) & Implementation Note (Oct 28, 2026)
- Federal Reserve FOMC Statement (September 16, 2026)
- FOMC Summary of Economic Projections (September 16, 2026, incl. June 2026 comparison)
- FOMC Meeting Calendar & U.S. Treasury Daily Yield Curve Rates (October 2026)